- Payroll
GeSY contributions in Cyprus: every rate, who pays it, and when
GeSY for 2026 is 2.65% for employees, 2.90% for employers, 4% for the self-employed and 2.65% on dividends, up to a €180,000 cap. See who pays each one and when.
 Sumly team
- Published
- 8 min read
On this page8 sections
GeSY, Cyprus's General Healthcare System, also written GHS, is funded by contributions on almost every kind of income a person receives. That covers salary, dividends, rent, pensions and self-employment profits. For 2026 the rates are 2.65% for employees, 2.90% for employers and 4% for the self-employed. Dividends and other personal income carry 2.65%. All of it is charged on total annual income up to €180,000. If you own a Cyprus limited company, you meet GeSY three times. Once on your salary as an employee, once on the same salary as the employer, and once on your dividends as a shareholder.
What is GeSY and who has to pay it?
GeSY is Cyprus's national health system, and almost everyone with an income pays into it. It's funded by contributions on income, not by general taxation, and that makes it broader than most people expect. Income tax has bands and exemptions, and the Special Defence Contribution skips non-doms entirely. GeSY reaches almost every income stream of almost every earner, at a low flat rate.
For a company owner, that means three separate charges. As an employee of your own company, you contribute on your salary. As the employer, the company contributes on the same salary. As a shareholder, you contribute on the dividends you draw. A self-employed person outside a company pays a single higher rate of 4% on their own income instead. The state adds its own 4.70% on top of everyone's contributions, which is how the fund holds together at rates this low.
General Healthcare System Law 89(I)/2001
the contribution obligation on income
Official sourceChecked 26 August 2026
What are the GeSY contribution rates in Cyprus for 2026?
Employees pay 2.65%, employers 2.90% and the self-employed 4%. Dividends and other personal income carry 2.65%. The rates haven't changed since 1 March 2020. GeSY lands on the same payslip as Social Insurance, so the table below shows both systems side by side. If you're budgeting a hire, you need the whole table. If you're budgeting a dividend, you need the GeSY rows for dividends and the cap.
| Employee GeSYDeducted from gross pay | 2.65% |
|---|---|
| Employer GeSYPaid by the company on top of the salary | 2.90% |
| Self-employed GeSYCollected quarterly with Social Insurance, with the balance self-assessed | 4% |
| GeSY on dividends, rent and other individual incomeCharged whatever your domicile | 2.65% |
| GeSY annual income capTotal income from all sources combined. Contributions above it can be reclaimed | €180,000 |
| Employee Social InsuranceDeducted from gross pay | 8.8% |
| Employer Social InsurancePaid by the company on top | 8.8% |
| Self-employed Social InsuranceOn notional insurable income by occupation | 16.6% |
| Employer-only fundsNever deducted from the employee. Social Cohesion has no cap | Redundancy 1.2% · HRDA 0.5% · Social Cohesion 2% |
| Maximum insurable earnings (Social Insurance ceiling)€5,742 a month, €1,325 a week. Separate from the €180,000 GeSY cap | €68,904 a year in 2026 |
On a €3,000 gross monthly salary, the employee has €79.50 of GeSY and €264 of Social Insurance deducted before PAYE, the income tax withheld from pay. The company adds €87 of employer GeSY, €264 of employer Social Insurance and €111 across the three employer-only funds. Total employer on-costs come to 15.4% of gross, so that €3,000 salary costs the company €3,462 a month. Budget hires from that figure, not the gross.
Social Insurance stops at maximum insurable earnings of €1,325 a week, €5,742 a month. The 2% Social Cohesion Fund has no ceiling at all. GeSY ignores both and runs on its own €180,000 cap. Our guide to Social Insurance in Cyprus covers that half of the payslip in full.
Do you pay GeSY on dividends, even as a non-dom?
Yes, and this is where the expensive surprises happen. Non-dom status is for Cyprus tax residents who aren't domiciled here, and it's worth a lot. It keeps you outside the Special Defence Contribution on dividends, interest and rent for up to 17 years. GeSY is a separate charge under a separate law, and your domicile doesn't matter to it.
So a non-dom's dividend carries zero SDC and full GeSY. Take a €100,000 distribution. The SDC line reads €0 and the GeSY line reads €2,650, as long as you're still under the annual cap. Founders ask us about this every time they model a distribution, because forum posts sum up the regime as "non-dom pays nothing on dividends". Build the 2.65% into the model from the start, and read our non-dom status guide for what the regime actually covers.
Is there a cap on GeSY contributions?
Yes. Contributions are charged on total annual income up to €180,000 per person. Income counts towards the cap in a fixed order: earnings first, then pensions, then other income such as dividends and rent. At the 2.65% rate, the most you pay in a year is €4,770. A self-employed person at 4% tops out at €7,200.
The cap is one ceiling across all your income. Say you take an €80,000 salary and a €150,000 dividend in the same year. Your total income is €230,000, but only €180,000 of it is contributable. The salary uses up €80,000 of the cap through payroll. The first €100,000 of the dividend carries 2.65%, and the last €50,000 carries nothing. Contributions collected above the cap are refundable. For contribution years from 2025 onwards, you apply to the Commissioner of Taxation for the refund. Each payer withholds without seeing your other income. So if you earn from several sources at once, track the running total during the year rather than discover an overpayment afterwards.
When is GeSY actually paid?
It depends on the income. On a salary it's paid monthly through payroll. On a dividend it's withheld at source when the dividend is paid. The self-employed pay quarterly, with a self-assessed balance. On salaries, the employee's deducted share and the employer's own share go on the monthly TD7, the employer's return of tax withheld from pay. Both are paid through Tax For All, the Tax Department's online portal, by the end of the month following the salary month, together with the PAYE withheld from the same payroll. Social Insurance follows the same rhythm. It's paid to the Social Insurance Services by the end of the calendar month following the contribution month.
Dividends from a Cyprus company are handled at source. The company withholds the 2.65% when it pays the dividend and declares it, together with any SDC, on form TD603, payable by the end of the month following the payment. You pay it yourself only where no Cyprus payer withholds. In practice that means foreign dividends and similar foreign income, settled through your own tax filings. Our companion piece on GeSY for company owners walks through the TD603 in detail.
The self-employed pay their 4% quarterly with Social Insurance, worked out on the notional insurable income set for their occupation. Any balance on actual income is self-assessed through the Tax Department in two semi-annual payments, due 31 July and 31 December for 2026.
Did the 2026 tax reform change GeSY?
No. The reform moved almost everything around GeSY. Corporate tax went to 15%, SDC on dividends dropped to 5% for domiciled residents on new profits, deemed dividend distribution was abolished, and the personal tax bands were rewritten. GeSY rates and the €180,000 cap came through untouched.
So the health contribution is now a bigger share of what a dividend costs. For a domiciled shareholder, a distribution of 2026 profits now carries 5% SDC plus 2.65% GeSY. For a non-dom it's the 2.65% alone. If you're re-running your salary versus dividend numbers after the reform, our salary vs dividends guide and the full 2026 tax reform guide have the worked comparisons.
How Sumly handles GeSY
GeSY never arrives alone. Every payroll run produces the employee deduction, the employer share, the Social Insurance lines and the PAYE, and each of those is both a filing and an entry in your books. Sumly's payroll add-on, €15 per employee per month, calculates Social Insurance and GeSY for every run. It emails each employee their payslip, prepares the employer filings and posts the whole run into the books the moment it completes. A person submits the filings: you on Base, Sumly on Plus, and your Sumly certified bookkeeper on Premium.
That last step is the one that saves year-end pain. Contributions become a liability on payroll day and a bank payment weeks later, and the two have to reconcile. Sumly's payroll posts into the same books the bank feed lands in, so each month's payment matches off against its liability on its own. Dividends get the same treatment. The distribution, its SDC and its withheld GeSY are booked together, so nothing waits to be rebuilt in December. If you're still deciding how much of this to run yourself, our explainer on whether you need an accountant in Cyprus covers where the line sits.
Questions Cyprus company owners actually ask
Common questions
Keep reading.
- Payroll
Hiring your first employee in Cyprus: the complete employer checklist
Registering as an employer, the ERGANI notice, 2026 rates and minimum wage, monthly deadlines and payslips. Sumly runs the payroll and books it, €15 per employee a month.
Sumly team8 min read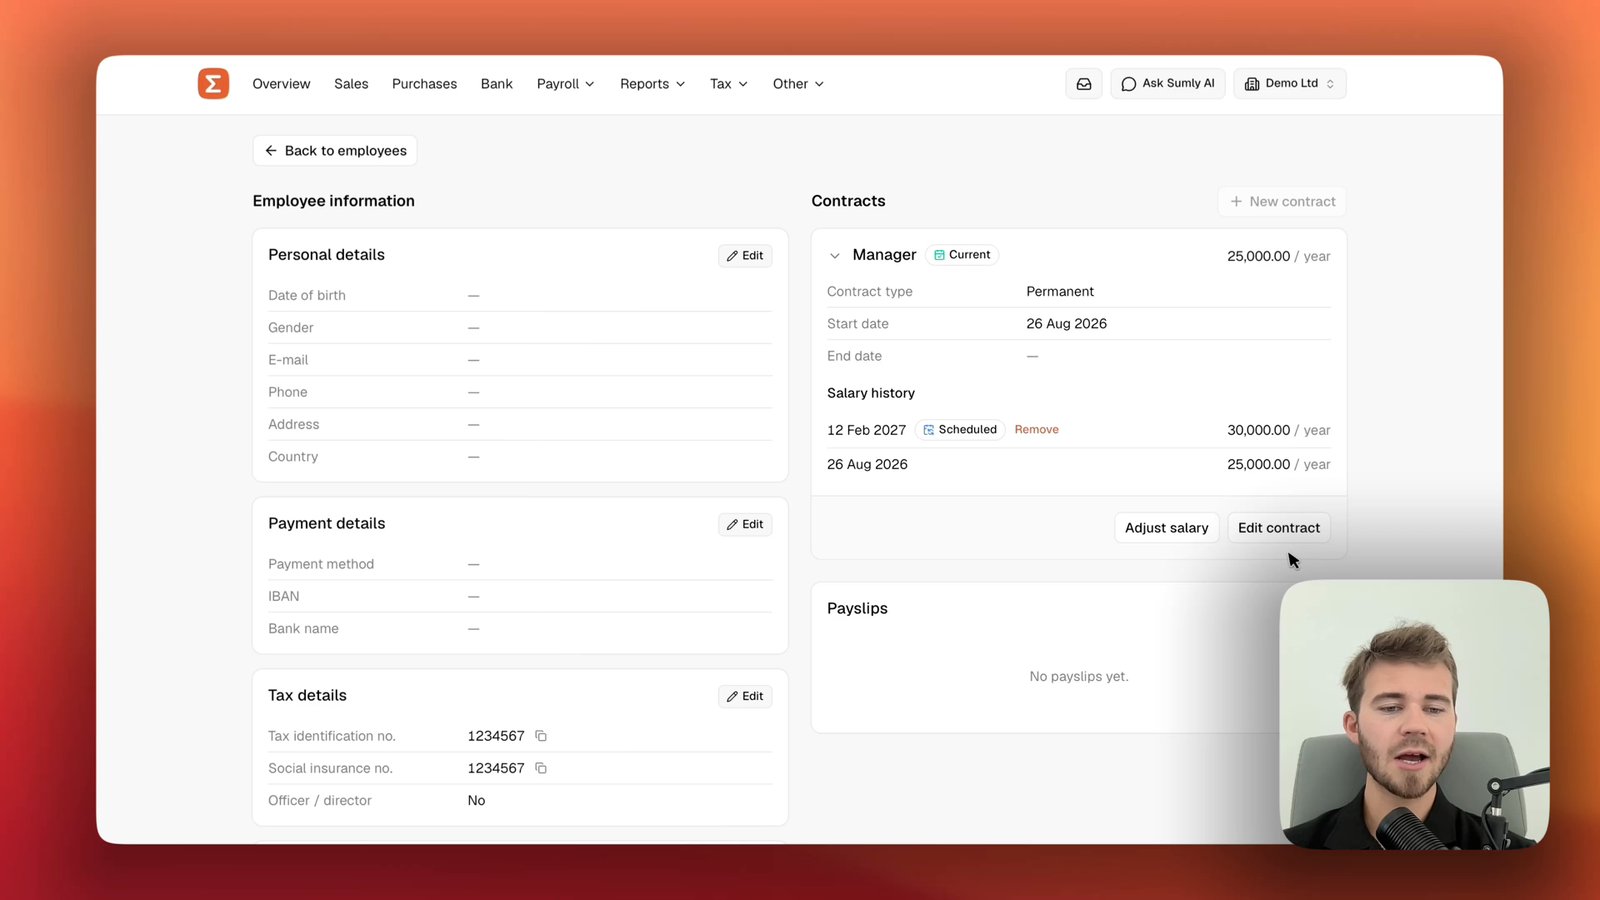
- Payroll
- Tax
TD59 in Cyprus: the employee declaration behind your PAYE
What Cyprus TD59 is, where to find the current English form, what employees give their employer and how to check the information before payroll.
Sumly team5 min read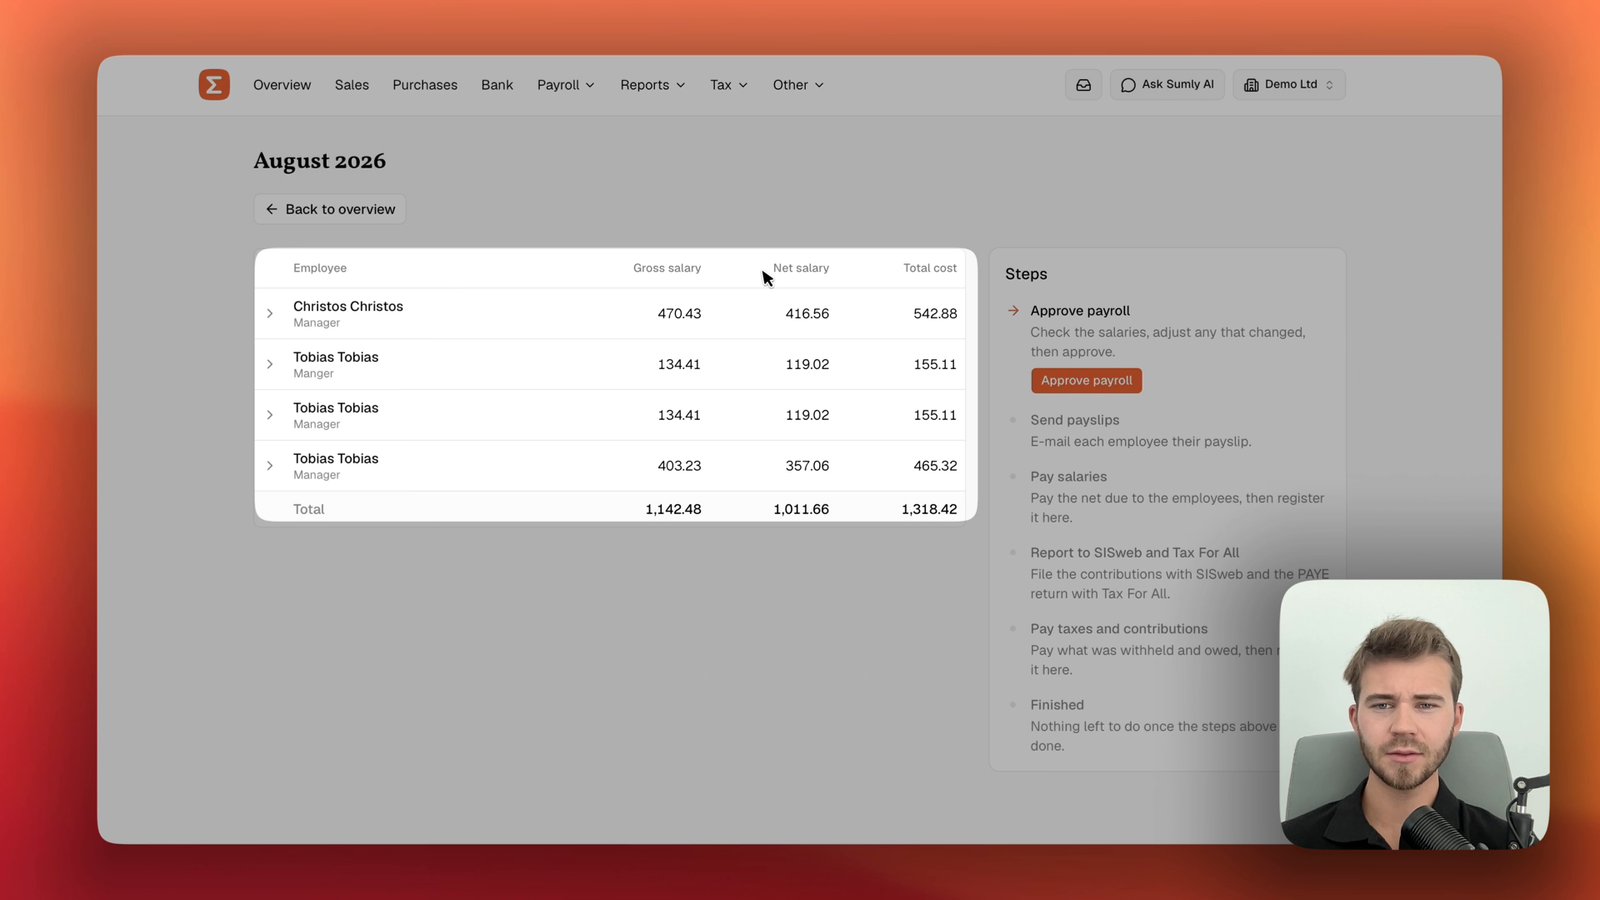
- Payroll
- Compliance
TD7 employer returns in Cyprus: monthly and annual filing through Tax For All
Prepare Cyprus TD7 employer returns from payroll, reconcile the annual totals, fix errors and keep proof of filing and payment in Tax For All.
Sumly team6 min read
Ready when you are.
Start a new company, or bring the one you already have.