- Banking
Bank reconciliation for a Cyprus company: the monthly routine that makes the books trustworthy
What bank reconciliation means for a Cyprus company, how the monthly routine runs, the five usual mismatches, and how open-banking feeds do most of the work.
 Sumly team
- Published
- Updated
- 9 min read
On this page8 sections
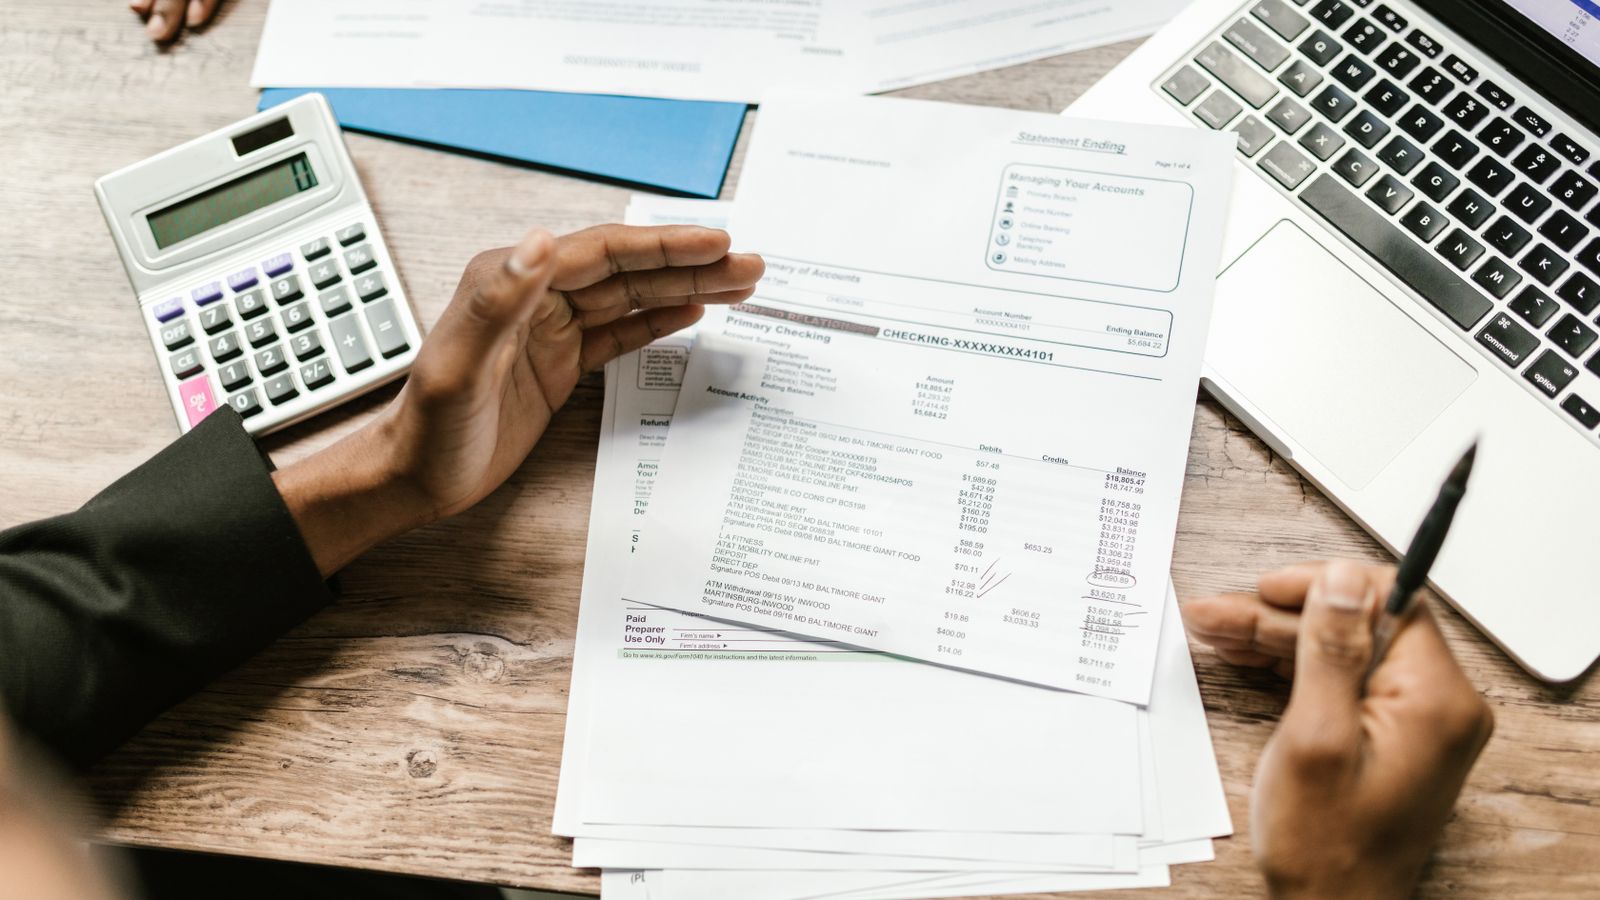
Bank reconciliation proves that your books and your bank tell the same story. You match every statement line to a ledger entry, explain anything left over, and confirm the closing balances agree. It's what makes every other number in your books believable, because the bank statement is the one record you didn't write yourself. Your VAT return, your profit and the financial statements your auditor signs all rest on a ledger that has been checked against the bank. If your Cyprus limited company does its own bookkeeping, build this habit first. It's also the part of the job open banking has automated furthest.
What does "reconciled" actually mean?
It means the bank balance in your ledger and the balance on the bank statement agree on the same date, and any gap between them is listed and explained. The bank account in your ledger mirrors the real one. Every sale paid, supplier settled, fee charged, salary run and transfer moves money at the bank. If the books are right, each one also creates a matching ledger entry. Reconciliation holds the two side by side for a period, usually a month, and proves they tell the same story.
The word has a precise meaning. An account is reconciled when the statement's closing balance and the ledger's balance on the same date agree, and anything separating them is listed, explained and expected to clear soon. Think of a transfer the bank hadn't processed by midnight, or a fee you hadn't booked yet. That list is the bank reconciliation statement. An accountant can read it in a minute and tell whether the books behind it are sound.
Balances that are only close don't count. Neither does a ledger where every transaction was imported but nobody reviewed them. It's the most common mistake we see in the books founders bring to us. The account looks complete because the feed filled it, while a pile of unmatched items grows slowly and nobody looks at it.
Why do the Tax Department and your auditor care?
Because it's the first check both of them run. An auditor forming an opinion on your financial statements agrees the year-end bank balances to the bank's own confirmation and reads the reconciling items. An account that reconciles cleanly shortens the whole audit. One that only reconciles through a long list of unexplained differences tells the auditor the rest of the ledger needs more digging, so the audit gets slower and more expensive. Our explainer on Cyprus audit requirements covers what the auditor looks for.
The Tax Department looks at it the same way. A VAT inspection compares the returns you filed with the books and the bank. The classic findings are receipts at the bank that never reached the sales ledger, and purchases booked with no payment behind them. Cyprus companies must keep books and records good enough to support the returns they file. Our guide to accounting records requirements covers what that includes and how long to keep them. A reconciled bank holds those records together, because it ties every document to a real movement of money.
You have a stake too. Your cash position, your profit and the VAT building up for next quarter only mean something when the ledger behind them has been proved.
What is the monthly routine?
Five steps take you from bank statement to proved balance, and they stay quick only if you do them every month. In order:
Get the statement for the period
Get one for every account that holds company money, whether current, savings, cards or payment platforms, each in its own currency. With a live bank feed you skip this step, because the transactions are already in.
Match every statement line to a ledger entry
Match customer receipts to the invoices they settle and supplier payments to the bills they pay. Match salaries, Social Insurance, GeSY health contributions and VAT payments to their control accounts, and transfers between your own accounts to each other. Leave no statement line without a partner.
Book what the bank knew and you did not
Bank charges, card fees, interest, currency conversion differences and direct debits usually show on the statement first. Enter them, with the bank's own advice as the document, so the ledger catches up with reality.
Investigate what is left
A statement line with nothing to match, or a ledger entry with no bank movement, usually points to an error. It might be a missing receipt, a duplicate booking, or money received for something you never invoiced. Park it somewhere visible rather than forcing it into a category.
Agree the closing balances and keep the proof
Keep the statement balance, the ledger balance and the list of reconciling items that explains any gap, dated and filed with the period. This is the document the auditor asks for.
Do this before every VAT return, because the return is only as good as the ledger behind it. Our walk-through of how to file a Cyprus VAT return assumes the bank is reconciled when the quarter closes. The deadline, the 10th day of the second month after the quarter ends, leaves plenty of room for a monthly routine. It leaves no room to rebuild six months of history first.
For the wider month-end close, follow the monthly bookkeeping checklist. The guides to Revolut Business bookkeeping and Stripe sales, fees and payouts answer the questions specific to those accounts.
What causes the differences and how do you resolve them?
Nearly every difference in a small Cyprus company comes from one of five places, and each has a standard fix.
Bank fees and charges. Account fees, transfer charges and card-acceptance fees taken before settlement reach the statement before anyone thinks to book them. Bank charges are exempt from VAT as financial services, so there's no VAT to reclaim on them. Book them as if 19% VAT were included and the VAT return comes out wrong without anyone noticing. Post them from the statement, with the bank's charge advice as the document.
FX differences. FX means foreign exchange. Say you invoice a US client $2,000 and book it at €1,840. The payment lands in your euro account as €1,815, because the rate moved and the bank took a spread. The customer hasn't short-paid you €25. That's a realised exchange loss, and it goes in its own account. If your company invoices or pays in more than one currency, read our guide to bookkeeping in foreign currency, because the same issue comes back at every month-end revaluation.
Timing. A payment made on the last day of the month that the bank processes on the first of the next. These are genuine reconciling items. List them and check they clear in the next period. If an item is still on the list three months later, timing is no longer the explanation, and someone needs to find out what it really is.
Card and payment-platform settlements. A card acquirer, the company that processes your card payments, or an online payment provider pays out one net amount for many sales. Its fees are already taken off, and the payout often comes days after the sales. Treat the provider as its own account. Sales land there gross, you book the fees there, and the payout is a transfer from the provider account to the bank.
Transfers between your own accounts. Moving money from Revolut Business to Bank of Cyprus, or from a euro to a dollar balance, creates a line at each end. Book it once as a transfer and it reconciles on both sides. Book it as income on one side and an expense on the other, and it inflates both and puts a wrong number into the VAT return.
Anything you can't explain goes to a suspense account, a clearly labelled holding account, and you chase it.
How do you reconcile Revolut Business or Wise alongside a Cyprus bank?
The same way, account by account. Many Cyprus companies keep a local bank account for salaries, tax payments and the counterparties who expect one. Alongside it they run Revolut Business or Wise for receipts in several currencies and cheaper international payments. Our guide to opening a business bank account in Cyprus covers how founders combine them, and how the market has consolidated since Hellenic Bank merged into Eurobank and AstroBank's operations moved into Alpha Bank. For the bookkeeping, the provider's licence and location don't matter. Each account, and each currency balance inside it, is a separate ledger account reconciled to its own statement.
A setup with several accounts stays clean if you're strict about movements and fees. Book every movement between your own accounts as a transfer, so a euro-to-dollar conversion inside Wise is a transfer plus an exchange difference, not a sale. Keep the provider's fee lines visible instead of netting them into the amounts they came out of. And reconcile every account to the same date, so the company's cash position is a sum of proved balances.
How do open-banking feeds change the job?
They do the typing and most of the matching, and leave the judgement to you. With open banking, you let an accounting platform read your bank transactions directly through the bank's regulated connection, instead of downloading statements and typing them in. The transactions arrive as they happen, with the bank's own reference, counterparty and amount. This access is an account information service under PSD2, the EU's payment services directive. It's read-only by design, regulated, and needs your explicit consent. The platform can see transactions and balances. It can't make payments or change anything at the bank.
Reconciliation then stops being a monthly event and becomes something that's always up to date. The ledger's bank account shows what the bank has processed. Matching runs by itself, because the platform holds both sides. It pairs each transaction with the invoice or bill it settles by amount, counterparty, reference and date. What's left is the short list it couldn't pair, such as a payment with no document, one settlement covering several invoices, or an amount that nearly matches. Those come from the same five differences above, and clearing them is where your few minutes a week go.
How does Sumly reconcile a Cyprus company's bank?
Through live, read-only open-banking feeds. Bank of Cyprus, Eurobank, Alpha Bank, Revolut Business and Wise are ready to use. Former Hellenic Bank accounts have their own entry in the feed list, under Eurobank. Over a hundred more banks can be connected on request. Read-only means Sumly can see your transactions and can never move your money.
As transactions arrive, Sumly matches them against the invoices you issued from it and the purchases its AI booked from your receipts and bills. You drop those in, or email them to your company's private Sumly inbox. So reconciliation happens by itself, not as a month-end chore. Foreign-currency amounts convert to euro automatically, and the document behind every entry stays linked to it for the audit trail.
On Base, what's left for you is the short list. You confirm the handful of items that need a person and chase the missing receipts. The VAT return then builds itself from books you've already proved, ready for you to review and submit. On Plus, Sumly files every return except the year-end accounts. The VIES statement lists your sales to businesses in other EU countries. On Premium, your Sumly certified bookkeeper does the review and the filing inside your own dashboard. If something on the bank looks unfamiliar, ask Sumly AI about your live books and you get an answer with the figures behind it. Your auditor can ask it too.
Questions people ask
Common questions
Keep reading.
- Bookkeeping
- Banking
- VAT
Stripe bookkeeping for Cyprus businesses: sales, fees and payouts
How to reconcile Stripe in your Cyprus company's books, with a worked example of gross sales, refunds, processing fees, payouts and unsettled balances.
Sumly team4 min read
- Banking
- Bookkeeping
Revolut Business bookkeeping for Cyprus companies
Keep Revolut Business transactions straight in your Cyprus books: separate currency balances, transfers, fees, source documents and month-end checks.
Sumly team4 min read- Banking
- Bookkeeping
Multi-currency bookkeeping for a Cyprus company: rates, VAT and bank accounts
How a Cyprus company keeps euro books while invoicing in dollars or pounds: which exchange rate to use, realised differences, and showing VAT in euro.
Sumly team9 min read
Ready when you are.
Start a new company, or bring the one you already have.